Evening edition · Thursday, 22 October 2026
Podium vs Print: "no fragmentation", and the widest French spread since 2011
Six days ago the Banque de France governor said the conditions for ECB help were not met. On Thursday France paid 173.58 basis points over Germany, and every other spread widened with it. He may still be right; the test he set is the one to watch.
“…today, those conditions are not met. We are not seeing financial fragmentation in the euro area.”
Emmanuel Moulin, Governor of the Banque de France and ECB Governing Council member, to AFP, 16 October 2026
173.58 bp
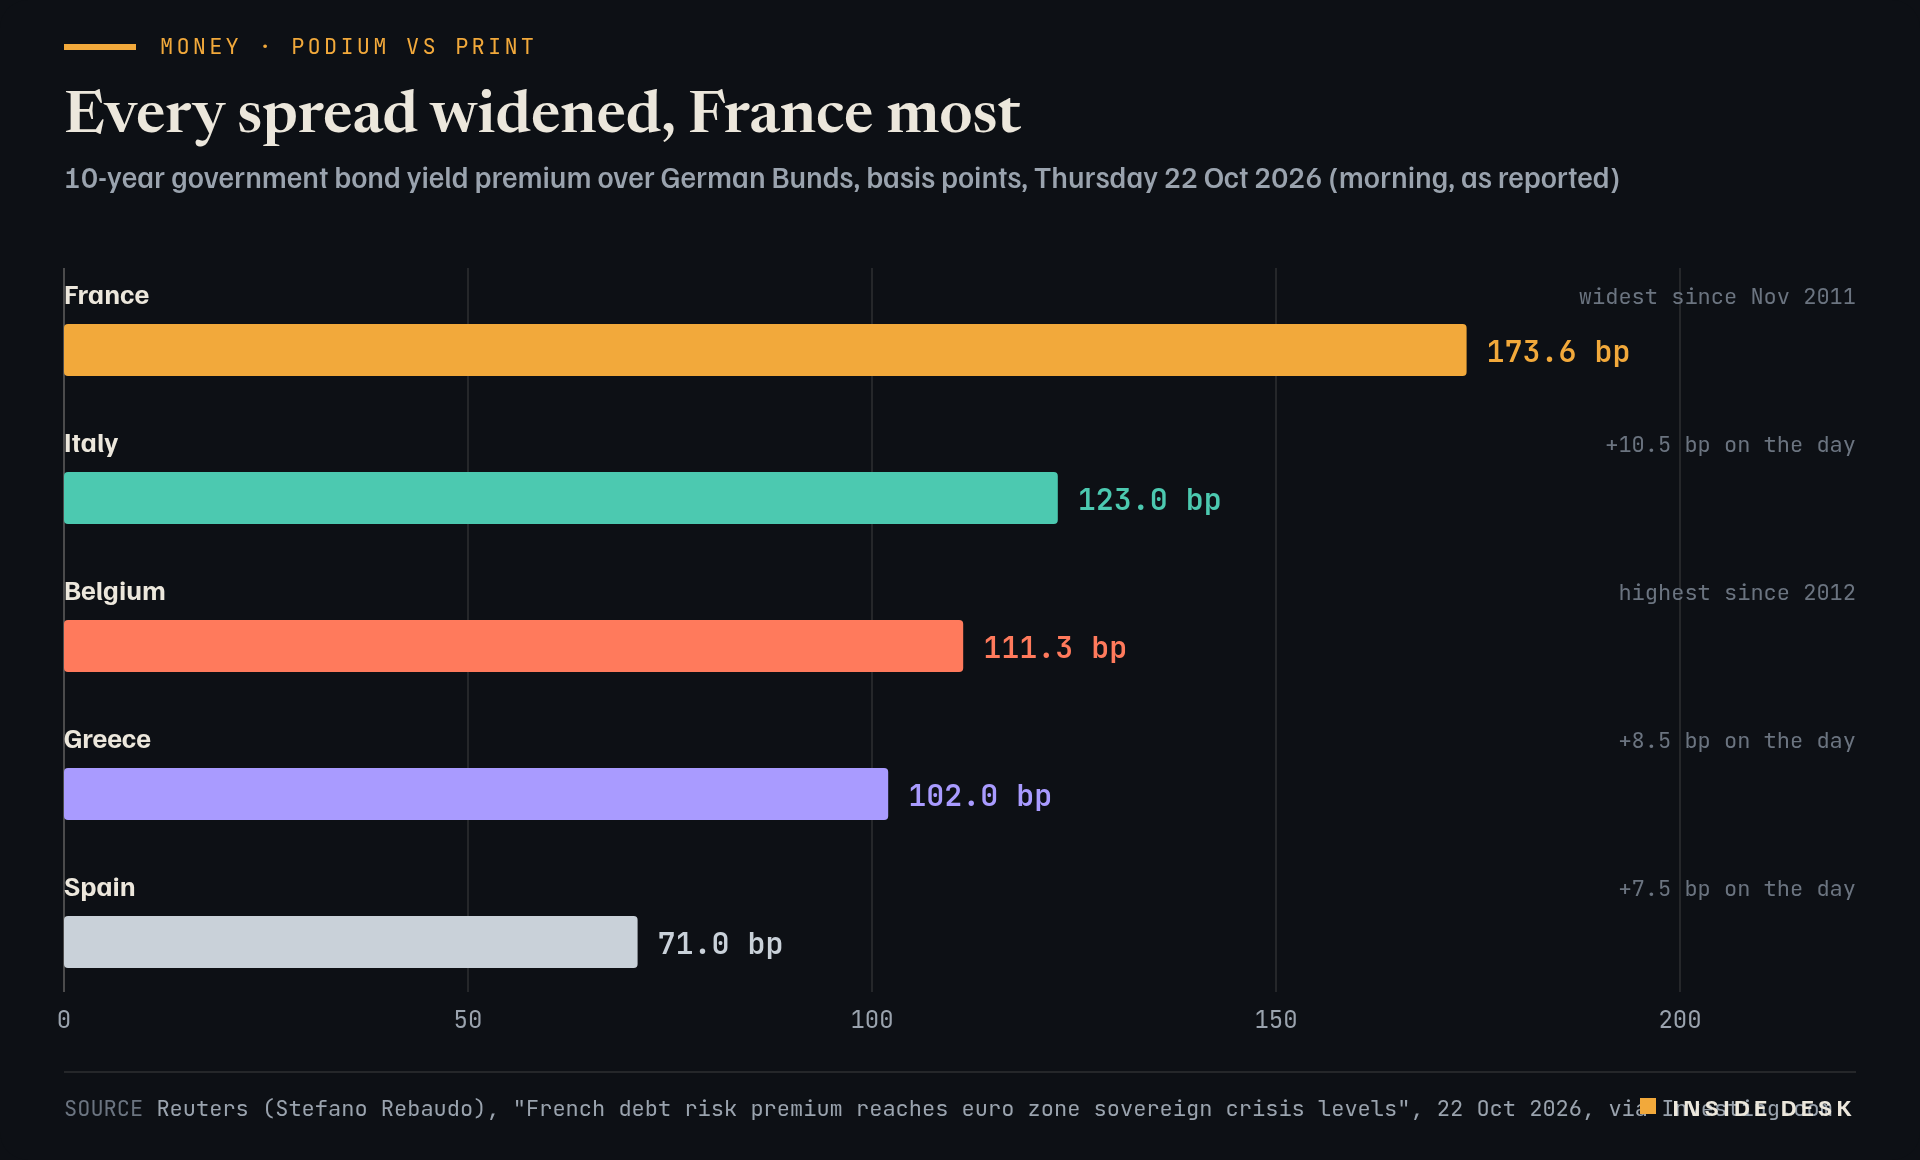
France's 10-year premium over German Bunds, its widest since November 2011; the French 10-year yield rose 11.5 bp to 5.11%, after touching 5.1415%, its highest since July 2002.
Euro area government bond market, as reported by Reuters, 22 October 2026, morning
The podium. On 16 October Emmanuel Moulin, governor of the Banque de France, told AFP that the ECB has instruments “when disorderly and unjustified market movements can disrupt the transmission of monetary policy”, but that “today, those conditions are not met. We are not seeing financial fragmentation in the euro area”1. He blamed the rise in French borrowing costs mainly on “uncertainties over the budget vote”, said banks and insurers could cope, and prescribed “fiscal consolidation” rather than central bank action1.
The print. On Thursday morning France’s 10-year yield rose 11.5 basis points to 5.11%, after touching 5.1415%, its highest since July 20022. The premium over German Bunds reached 173.58 basis points, the widest since November 2011, in the euro debt crisis2. German 10-year yields fell 4 basis points to 3.38% on safe-haven buying2. And France was not alone:
Bar chart of 10-year bond spreads over German Bunds on the morning of 22 October 2026, as reported by Reuters: France 173.58 basis points, its widest since November 2011; Italy 123; Belgium 111.28, its highest since 2012; Greece 102; Spain 71. All five widened on the day.
Source Reuters (Stefano Rebaudo), "French debt risk premium reaches euro zone sovereign crisis levels", 22 Oct 2026, via Investing.com. Figures as reported by the named organisations; facts cited with attribution.
Data (CSV) · SVG · PNG

Latest values as a table
| Value | |
|---|---|
| France | 173.58 bp |
| Italy | 123 bp |
| Belgium | 111.28 bp |
| Greece | 102 bp |
| Spain | 71 bp |
Belgium’s spread widened more than 10 basis points to 111.28, its highest since 2012; Italy’s rose 10.5 to 123, Greece’s 8.5 to 102 and Spain’s 7.5 to 712. By midday the French yield was still at 5.09%, according to Sharecast4.
The gap. Desk arithmetic: in the week since Moulin spoke, the French yield has gone from “close to 5%”1 to above 5.1%2, and the move on Thursday came while the German yield fell. That is the shape of a country premium, not of a broken market. But Moulin’s own test was fragmentation across the euro area, and on Thursday every spread on the Reuters list widened at once2. One day of that is a mood. A month of it would start to look like the thing he said he was not seeing.
Verdict. The podium holds, for now. Moulin did not promise calm; he set a threshold, and a threshold is more useful to you than a reassurance, because you can check it. Nordea’s reading is the same in other words: unchanged rates next week, a December hike still likely, unless the market turns “clearly disorderly” well beyond France3. The fix Moulin named sits in parliament, not in Frankfurt1. Nothing here is advice.
What to watch
- The ECB decision on 29 October: Nordea calls anything other than unchanged rates "a surprise", and money markets price the deposit rate at 2.73% by December2,3.
- Whether the widening stays a French story or spreads: Nordea says a "clearly disorderly" reaction beyond France could derail a December hike3.
- Saturday's planned protests in France, and the budget vote Moulin named as the main cause of the rise1,2.
A spread is a sentence the market writes about a budget, not about a central bank.
Sources
- ECB's Moulin: No Case for ECB Bond Market Intervention as French Yields Rise — Econostream Media, 16 Oct 2026.
- French debt risk premium reaches euro zone sovereign crisis levels — Reuters via Investing.com, 22 Oct 2026.
- European Central Bank: Communication focus as French spreads widen — FXStreet (Nordea), 22 Oct 2026.
- Europe midday: Stocks slump as oil rises; Hermes slides on results — Sharecast News, 22 Oct 2026.
Every figure in this piece traces to a source above or to the desk’s own arithmetic on those sources, marked as such. Quotations are short and attributed. Spot an error? Write to the desk; corrections are logged on the method page.
Commentary for information only. Not investment, legal, tax, medical or political advice. Not an offer or solicitation. Analysis may be incomplete or wrong. Charts show published public data, not a trading feed; binding numbers live with the institutions that publish them.