Evening edition · Friday, 13 November 2026
Less demand, a dearer Saturday: the auction that refused to follow the calendar
Saturday's power was bought on Friday at €197.72, more than Friday's. Meanwhile the oil watchdog says the barrel is back in surplus and gas had its dearest week in a while. Read the invoices, not the mood.
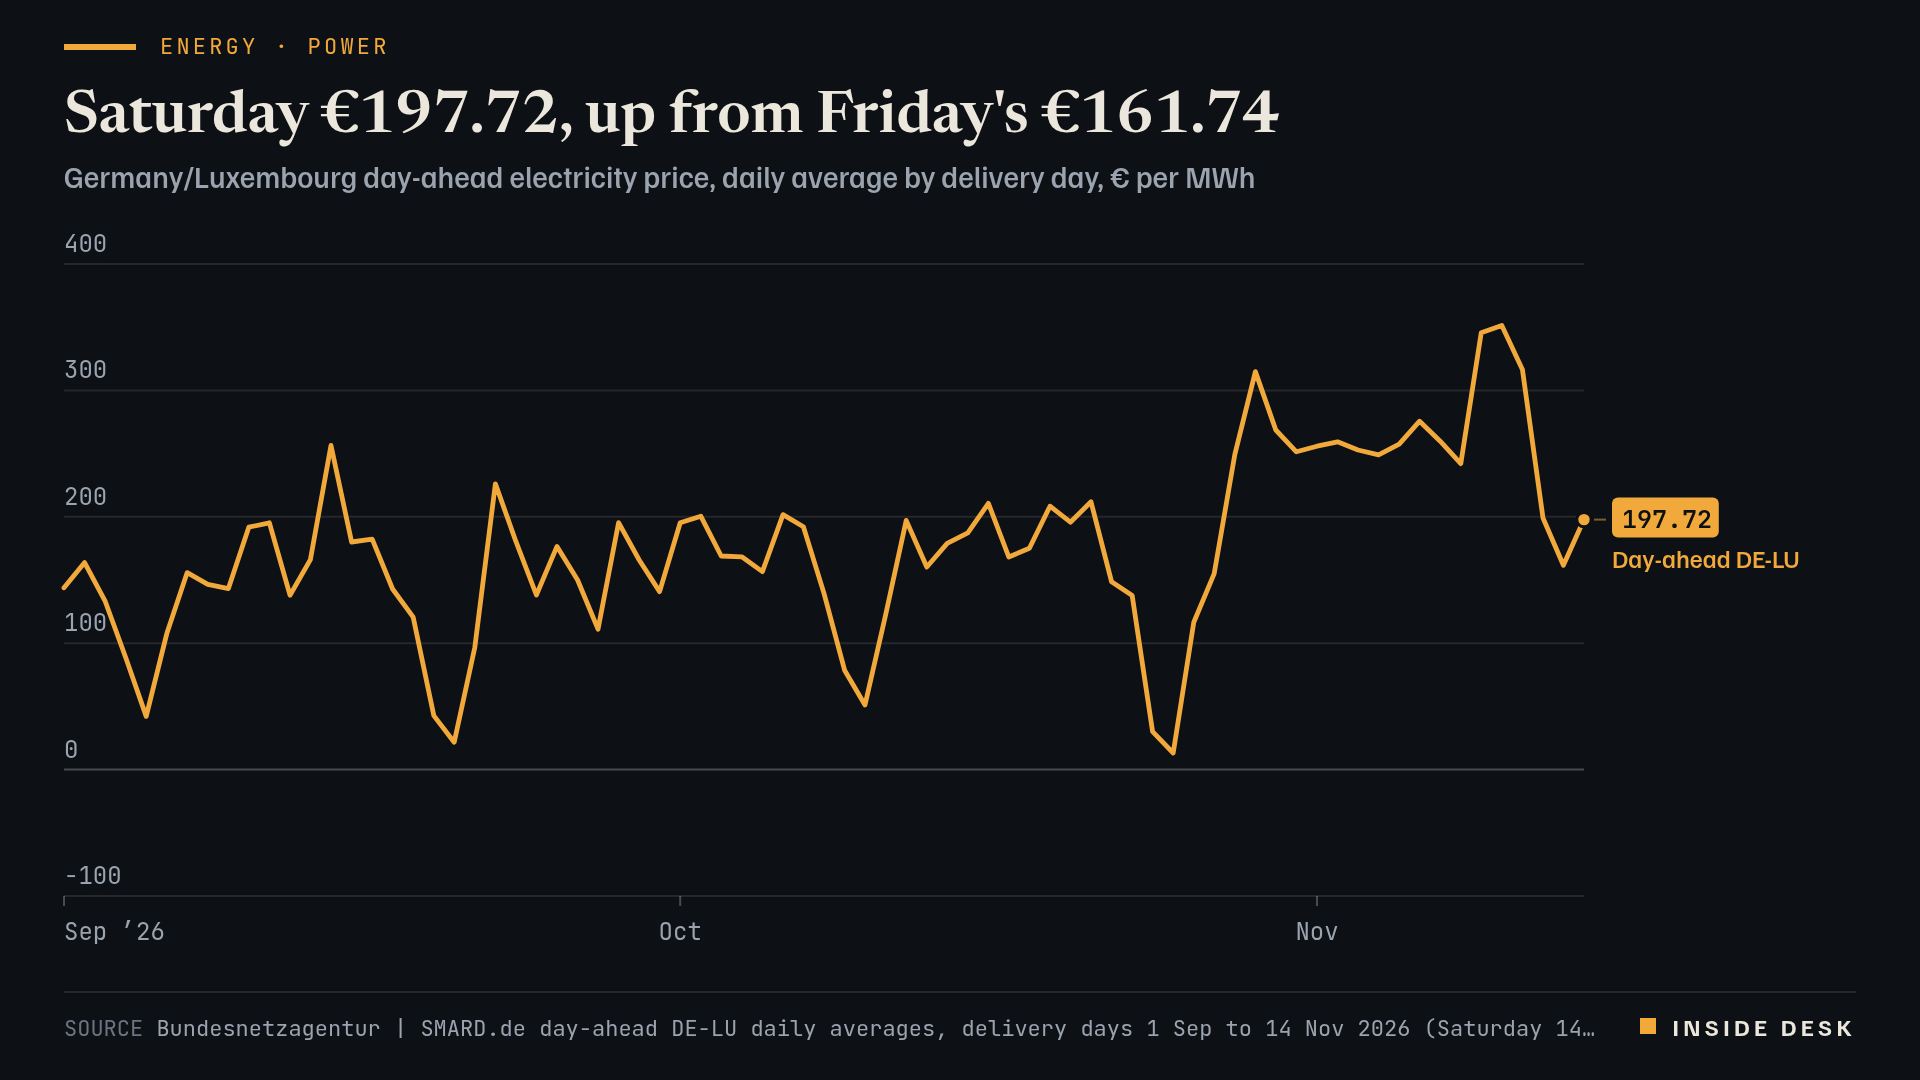
You would expect a Saturday to be cheap. Factories idle, offices dark, demand down. The auction for Saturday 14 November cleared on Friday, and it says otherwise. Delivery on Saturday will average €197.72 per megawatt hour for Germany and Luxembourg, against €161.74 for Friday1. Desk arithmetic: that is €35.98, or about 22%, dearer than the day before, and it ends three straight falls since Tuesday’s record €351.481.
The forecasters do not expect more demand. SMARD’s forecast puts Saturday’s consumption at about 1,252.8 GWh, against 1,449.3 GWh for Friday2. Desk arithmetic: roughly 196 GWh, or 13.6%, less power wanted, and a higher price for it. Something else has to give, and the one public number that would tell us what, Saturday’s wind forecast, had not been published when we checked at 16:32 CET2. We will not fill that gap with a guess.
Line chart of the daily average German-Luxembourg day-ahead electricity price from 1 September to 14 November 2026, in euros per megawatt hour. It falls to €13.12 on Sunday 25 October, climbs to €314.85 on Thursday 29 October and stays between €242.13 and €275.64 from 2 to 8 November. In the week of 9 November it reads €345.64 on Monday, a record €351.48 on Tuesday, €316.65 on Wednesday, €199.05 on Thursday and €161.74 on Friday. The latest value is €197.72 for delivery on Saturday 14 November, €35.98 above Friday and €62.11 below the previous Saturday, 7 November, at €259.83.
Source Bundesnetzagentur | SMARD.de day-ahead DE-LU daily averages, delivery days 1 Sep to 14 Nov 2026 (Saturday 14 Nov €197.72, auction of 13 Nov), retrieved 13 Nov 2026, 16:31 CET · CC BY 4.0. Bundesnetzagentur | SMARD.de, market data. CC BY 4.0.
Data (CSV) · SVG · PNG

Latest values as a table
| Date | Day-ahead DE-LU |
|---|---|
| 2026-11-09 | 345.64 |
| 2026-11-10 | 351.48 |
| 2026-11-11 | 316.65 |
| 2026-11-12 | 199.05 |
| 2026-11-13 | 161.74 |
| 2026-11-14 | 197.72 |
Keep the week in proportion. Saturday’s €197.72 is still €62.11 below the previous Saturday, 7 November, at €259.831. Desk arithmetic: about 24% cheaper week on week. One dearer day after a windy fall is a correction in the ledger, not a reversal of it.
Friday was the windy one. The regulator’s forecast for Friday was about 682.1 GWh of onshore wind and 137.4 GWh offshore2. Desk arithmetic: 819.5 GWh together, about 1.7 times Thursday’s realised 480 GWh. By 16:00 CET the meters had already logged about 441.1 GWh onshore and 93.5 GWh offshore2: 534.6 GWh in sixteen hours, more than all of Thursday (desk arithmetic). Friday’s cheapest hour, 12:00 to 13:00, cost €90.511; its dearest, 17:00 to 18:00, €226.201.
Read the hours, not the average. Saturday’s cheapest hour is 12:00 to 13:00 at €146.28; the dearest is 17:00 to 18:00 at €263.371. Desk arithmetic: a spread of €117.09 inside one day, wider than the gap between Friday and Saturday’s averages three times over. If you are on a dynamic tariff, the washing machine at lunch and the oven after seven is not lifestyle advice; it is the published price list1. On a fixed tariff, none of this reaches your bill this week.
Gas had a dear week. In the dark evening hours, gas plants are often the ones bidding, so the fuel’s price is never far from yours. Investing.com reported the Dutch TTF front-month contract up 4.2% to €96.18 per megawatt hour on Friday, locking in a weekly gain of about 12%, after President Trump said Washington no longer needed a deal with Tehran3. The same report notes EU storage at 71% full3. The report calls physical supplies “fundamentally stable” and puts the rise down to a geopolitical risk premium3. You are paying for insurance, not for scarcity.
Oil tells the opposite story. The International Energy Agency’s November Oil Market Report, published on Friday, says global supply rose by 2.3 million barrels a day to 105.4 mb/d in October, and that observed inventories rose by 52 million barrels, the first increase since June4. North Sea Dated crude, the agency writes, fell from $136 a barrel on 8 October to around $93 “at the time of writing”4. Its balances “suggest that the global oil market will return to a surplus” in the fourth quarter4. Brent traded between $95.06 and $97.04 during the London session, per Newsquawk, nudged up by reports that Israel’s spy chief was in Washington5.
There is a catch the IEA puts in plain words. Diesel in Europe, at close to $180 a barrel, is still 77% above pre-war levels, and on-land oil stocks are the lowest since at least 20164. Barrels are back on water; they are not yet in your tank.
For you. Three markets, three directions, one Friday: power up for the weekend, gas up for the week, crude drifting lower for the month. None of them was moved by a speech so much as by a forecast, a storage figure and an auction result, each published in public. That is the machinery worth trusting. Nothing here is investment advice.
What to watch
The calendar says weekend; the auction says read the hours.
Sources
- Marktdaten: Großhandelspreise DE/LU day-ahead, hourly and quarter-hourly (filter 4169), delivery 7 to 14 Nov 2026 — Bundesnetzagentur | SMARD.de, retrieved 13 Nov 2026, 16:31 CET.
- Marktdaten: Prognostizierter Stromverbrauch, Prognostizierte und Realisierte Erzeugung (wind onshore, wind offshore), 12 to 14 Nov 2026 — Bundesnetzagentur | SMARD.de, retrieved 13 Nov 2026, 16:32 CET.
- European gas logs 12% weekly surge as U.S.-Iran diplomatic hopes collapse — Investing.com, 13 Nov 2026.
- Oil Market Report - November 2026 — International Energy Agency, 13 Nov 2026.
- Newsquawk European Market Wrap - 13th November 2026 — Newsquawk, 13 Nov 2026, 16:20 CET.
Every figure in this piece traces to a source above or to the desk’s own arithmetic on those sources, marked as such. Quotations are short and attributed. Spot an error? Write to the desk; corrections are logged on the method page.
Commentary for information only. Not investment, legal, tax, medical or political advice. Not an offer or solicitation. Analysis may be incomplete or wrong. Charts show published public data, not a trading feed; binding numbers live with the institutions that publish them.