Evening edition · Wednesday, 11 November 2026
0.37% from the high, and a bond market on holiday
Europe spent Wednesday just below its records, carried by chips, oil and a turbine maker's invoices. US Treasuries said nothing: they were shut.
Europe spent Wednesday close enough to its records to see them, and did not quite touch them. At 16:16 CET the Stoxx Europe 600 stood at 660.97, up 0.40% on the day, against a 52-week high of 663.41; its best moment of the day was 663.361. Germany’s DAX was up 0.91% at 26,587.90 at 16:31 CET, after a day’s high of 26,659.42, beneath a record of 26,692.901. Desk arithmetic: the Stoxx 600 was 2.44 points, or about 0.37%, short of the high, and the DAX 105 points, or about 0.39%. These are afternoon values, not closes; the cash session ends at 17:30 CET.
You will read “near record” in a lot of places tonight. It is accurate, and it is also the least interesting thing about the day. What moved Europe was mostly a set of invoices.
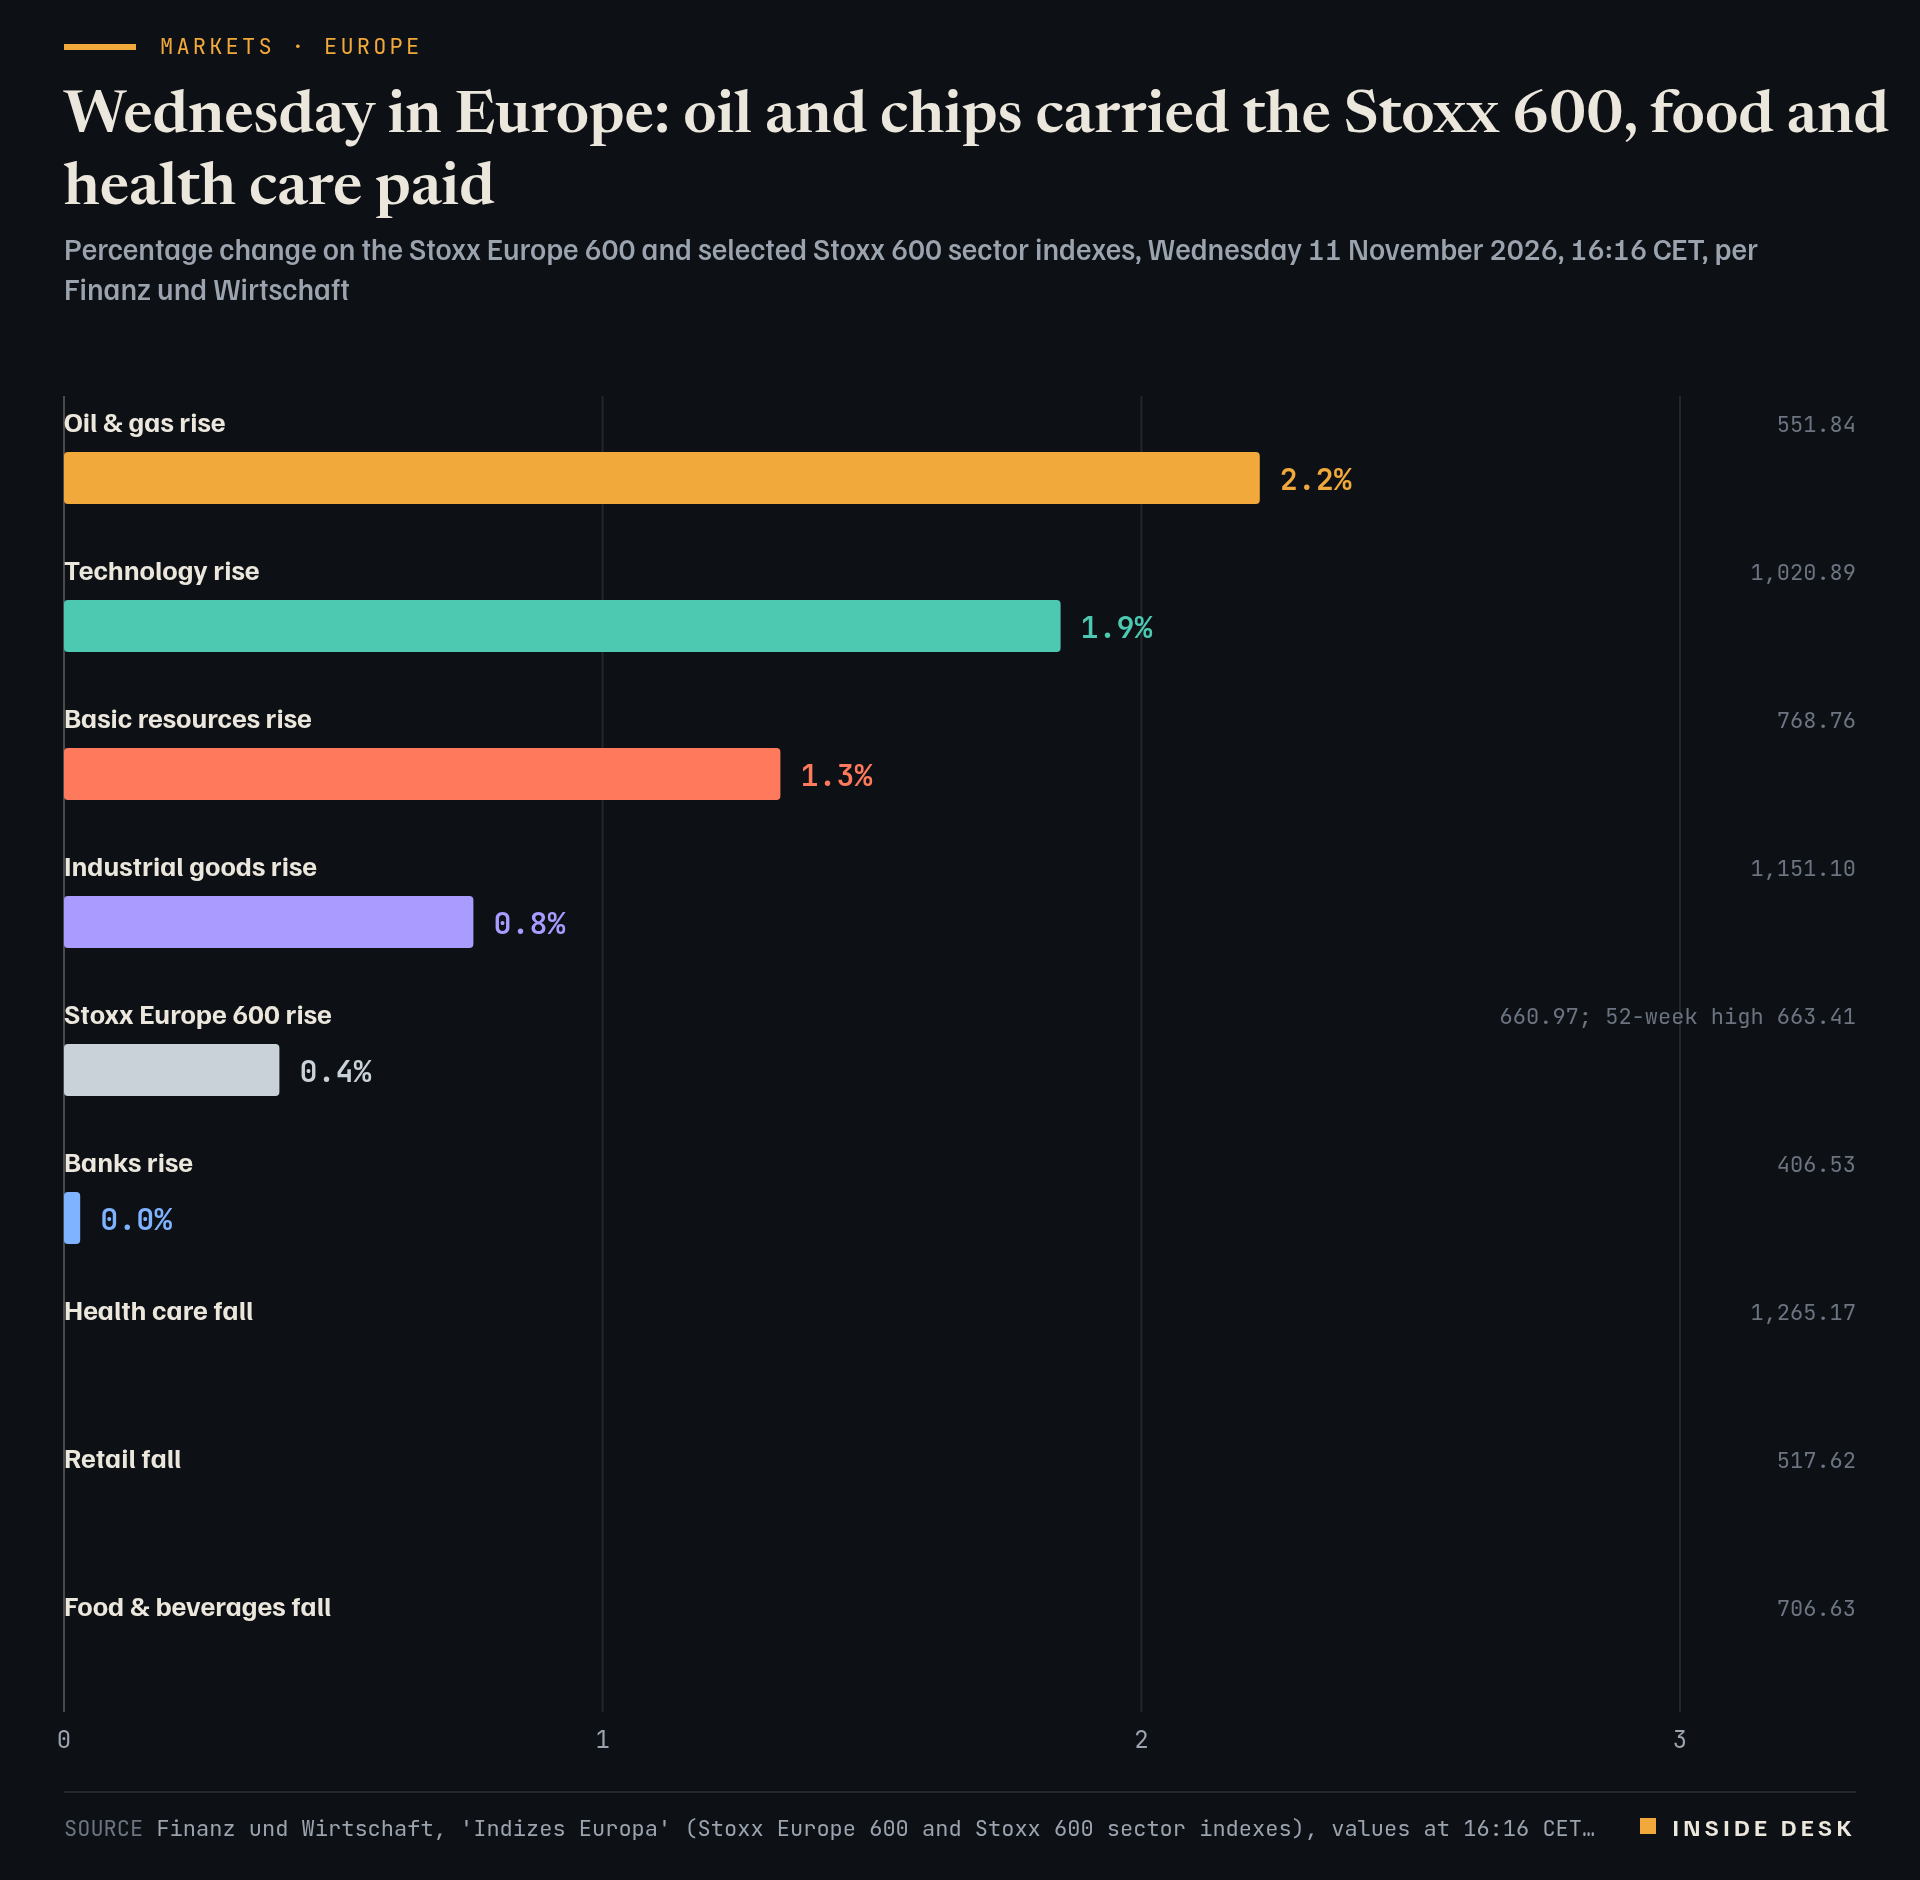
Bar chart of Wednesday 11 November 2026 percentage changes at 16:16 CET, per Finanz und Wirtschaft: Stoxx 600 oil and gas up 2.22 percent, technology up 1.85 percent, basic resources up 1.33 percent, industrial goods up 0.76 percent, the Stoxx Europe 600 up 0.40 percent to 660.97, banks up 0.03 percent, health care down 0.37 percent, retail down 0.45 percent and food and beverages down 0.86 percent. These are intraday snapshot levels, not closes.
Source Finanz und Wirtschaft, 'Indizes Europa' (Stoxx Europe 600 and Stoxx 600 sector indexes), values at 16:16 CET, 11 Nov 2026; intraday snapshot, not closing levels; retrieved 11 Nov 2026 · reported figures. Figures as reported by the named organisations; facts cited with attribution.
Data (CSV) · SVG · PNG

Latest values as a table
| Value | |
|---|---|
| Oil & gas rise | 2.22% |
| Technology rise | 1.85% |
| Basic resources rise | 1.33% |
| Industrial goods rise | 0.76% |
| Stoxx Europe 600 rise | 0.4% |
| Banks rise | 0.03% |
| Health care fall | -0.37% |
| Retail fall | -0.45% |
| Food & beverages fall | -0.86% |
The invoices. The first came from New York overnight. CoreWeave, the AI cloud provider that has become the market’s thermometer for AI spending, reported better-than-expected revenue and strong demand, and European chip equipment makers rose in sympathy: BE Semiconductor and ASM International were up more than 4% each in the morning, ASML and STMicroelectronics more than 3%3. ASM added a share buyback of up to €300 million2. By 16:16 CET the Stoxx 600 technology index was up 1.85%1.
The second came from Munich. Siemens Energy rose 7.7% in the morning2 after a year in which revenue rose 15.5% to €44.2bn, operating profit before special items more than doubled to €5.49bn, and the dividend was raised to €2.30 a share from 70 cents, with up to €9bn more in buybacks to 20307. That is not a story about a mood. It is a story about turbines and grid equipment ordered, built and paid for.
Not every invoice was welcome. Vestas fell 8% after narrowing its outlook, Brenntag 4.5% despite confirming its own, and CSG 23% after cutting its margin forecast2,3. The market can still tell one balance sheet from another. That is a healthier sign than any record.
The oil. The Stoxx 600 oil and gas index rose 2.22% by 16:16 CET, the best sector on the board1. Brent was up $1.32, or 1.4%, at $92.81 a barrel, after Iran’s security chief said Tehran would not allow enriched nuclear material to leave the country; Washington wants nuclear matters in any initial negotiation6. Brent has still fallen about 21% since the start of the month, CNBC notes6. One sentence from Tehran moved a dollar and change; eleven days of diplomacy have moved about a fifth of the price. Keep the proportions.
The quiet one. On the other side of the Atlantic, US stocks opened on Veterans Day, and the US bond market did not: SIFMA had recommended a full close for dollar-denominated government and corporate bond trading5. At 15:49 CET the S&P 500 was up 0.76% at 7,578.07 and the Nasdaq Composite up 1.16% at 25,354.34, while the Dow was down 0.13% at 52,162.064. CoreWeave was up 12.7% and Nvidia 2.4%, after Nvidia had shed about $430 billion of market value in the previous two sessions4. Traders still treat a Fed rate rise in December as certain, with an 11.5% chance of a half-point move, according to the CME FedWatch tool cited by Reuters4.
The dull machinery. In Wiesbaden, the statistics office confirmed October German inflation at 2.8%, down from 3.3% in September, with prices down 0.2% on the month and core inflation, excluding food and energy, slowing to 2.1% from 2.4%8. In Riga, Bundesbank President Joachim Nagel said interim assessments pointed to “a stronger recovery than we were expecting in the summer” and that growth “is likely to accelerate in the fourth quarter”, while warning the recovery is “not yet broad-based”9. Neither line will trend. Both matter more than a record.
For you. A day near the top is a good day to read what is underneath it: order books, dividends paid out of cash, and a price index that stopped climbing. Records come and go; the paperwork stays. Nothing here is investment advice.
What to watch
- Thursday 12 November: the US Treasury cash market reopens after Veterans Day and gives its first full reply to Tuesday's price figures5,4.
- US producer prices for October, due Friday 13 November at 14:30 CET.
- Whether the Stoxx 600 closes above its 52-week high of 663.41; at 16:16 CET it stood at 660.971.
A record is a number the market has already paid. The invoice behind it is the part worth reading.
Sources
- Indizes Europa — Finanz und Wirtschaft, 11 Nov 2026, 16:16–16:31 CET.
- European Shares Edge Higher As AI Concerns Ease (RTTNews) — finanzen.ch, 11 Nov 2026, 10:16 CET.
- European shares near record high as earnings absorb tech volatility — Investing.com, 11 Nov 2026.
- US STOCKS-S&P 500, Nasdaq rise as CoreWeave results ease AI spending worries (Reuters) — Devdiscourse / Reuters, 11 Nov 2026, 16:11 CET.
- SIFMA Fixed Income Market Close Recommendation for the U.S. Veterans Day Holiday — SIFMA, 28 Oct 2026.
- Oil up 1% after Iran says no nuclear material will leave the country — CNBC, 11 Nov 2026.
- Siemens Energy delights investors with dividend hike and share buyback (Reuters) — MarketScreener, 11 Nov 2026, 07:39 CET.
- German October inflation eases to 2.8% as expected; core slows to 2.1% — Investing.com, 11 Nov 2026.
- German growth stronger than expected, seen picking up: Bundesbank chief — RTÉ, 11 Nov 2026, 12:03 CET.
Every figure in this piece traces to a source above or to the desk’s own arithmetic on those sources, marked as such. Quotations are short and attributed. Spot an error? Write to the desk; corrections are logged on the method page.
Commentary for information only. Not investment, legal, tax, medical or political advice. Not an offer or solicitation. Analysis may be incomplete or wrong. Charts show published public data, not a trading feed; binding numbers live with the institutions that publish them.